Independent auditing and internal auditing are two indispensable pillars in the risk management system of modern businesses in Vietnam. From the perspective of MAN – Master Accountant Network, confusing the roles of these two types of auditing often leads to wasted resources or the overlooking of serious financial and operational risks. With increasingly stringent economic and tax laws from 2026 onwards, businesses need to clearly understand the position of each type of auditing to optimize management efficiency.
The development of the financial market demands that organizations have a keen eye for transparency and compliance. This article, based on 30 years of practical experience, will clarify the core differences and the symbiotic relationship between independent auditing and internal auditing. We will provide managers with the most comprehensive overview to make sound decisions for sustainable development.
Summary of key aspects of independent auditing and internal auditing.
Independent auditing is a third-party service that verifies the reliability of financial statements for external parties, while internal auditing is a management tool that helps the organization operate smoothly and prevents internal risks. Businesses need both types of auditing to ensure legal compliance and optimize operational performance. While independent auditing focuses on the accuracy of past figures, internal auditing focuses on improving the current and future processes of the business.
Overview of internal audit
Internal audit It is an independent, objective function established within the organization. This function goes beyond simply checking numbers; more importantly, it assesses the effectiveness of internal control system.
Definition and legal basis
Based on Accounting Law 2015Internal auditing is understood as the activity of examining, evaluating, and monitoring the completeness and appropriateness of internal policies, procedures, and regulations. The ultimate goal of internal auditing is to ensure that all business operations are on track, preventing errors and fraud.
In large-scale businesses For listed companies, internal auditing acts as an early warning system. According to experts at MAN – Master Accountant Network, without internal auditing, business leaders are like steering a large ship in fog without radar to warn of obstacles.
The role of internal audit in governance
Internal audit performs three core tasks:
- Assess the internal control system: Determine whether current processes are robust enough to prevent asset loss.
- Risk management support: Identifying potential risks in operations, from process risks to legal compliance risks.
- Contributing to improved operational efficiency: Providing recommendations to streamline and improve workflows.
Overview of independent auditing
Unlike internal auditing, independent audit It is a professional service provided by external auditing firms.
Definition and legal role
According to Independent Auditing Law 2011This involves examining and providing an opinion on a company's financial statements. The opinion of an independent auditor is an important basis for shareholders, investors, banks, and tax authorities to assess the financial health of the company.
In Vietnam, independent auditing is not only a right but also a mandatory obligation for many types of businesses, especially public companies, state-owned enterprises, and credit institutions.
Value added for businesses
An independent audit report with a full unqualified opinion helps a business:
- Increase your credibility with lenders: Banks often require audited financial statements when considering credit limits.
- Building trust with investors: Investors need objective figures that are not manipulated.
- Minimizing tax risks: Audit reports are crucial documents for explaining matters to tax authorities during routine inspections or audits.
Distinguishing between independent audit and internal audit
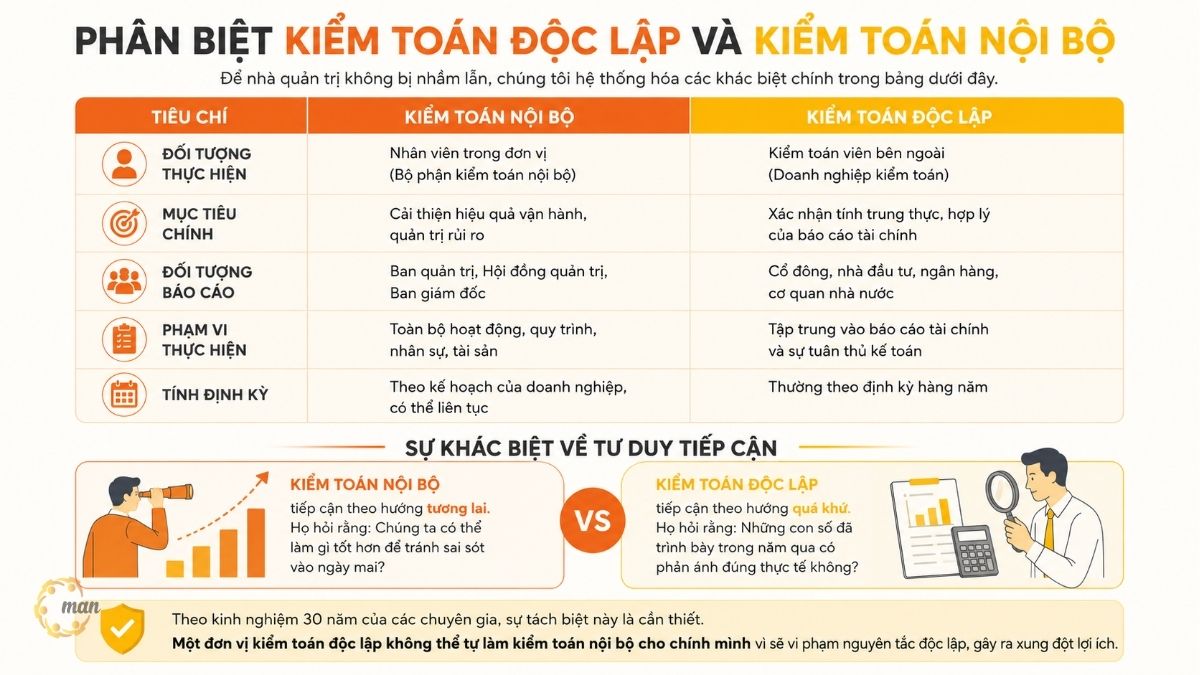
To avoid confusion for managers, we have systematized the main differences in the table below.
| Criteria | Internal audit | Independent audit |
| The subject of execution | Staff within the unit (Internal Audit Department) | External auditors (Auditing firms) |
| Main objective | Improve operational efficiency and risk management. | Verify the accuracy and fairness of the financial statements. |
| Reporting entities | Board of Directors, Management Board, Executive Board | Shareholders, investors, banks, government agencies |
| Scope of implementation | All operations, processes, personnel, and assets. | Focus on financial reporting and accounting compliance. |
| Periodicity | According to the company's plan, it can be continuous. | Usually on an annual basis |
Differences in approach and mindset:
Internal auditors take a forward-looking approach. They ask: What can we do better to avoid mistakes tomorrow? Meanwhile, independent auditors take a past-looking approach. They ask: Do the figures presented over the past year accurately reflect reality?
According to the 30 years of experience of experts at MAN – Master Accountant Network, this separation is necessary. An independent auditing firm cannot conduct its own internal audits because it would violate the principle of independence and create a conflict of interest.
Important relevant legal documents
Accounting Law No. 88/2015/QH13
Date of issue: November 20, 2015
Main content:
- Internal control regulations.
- Regulations regarding internal auditing.
- Responsibilities for organizing accounting work.
Law on Independent Auditing No. 67/2011/QH12
Date of issue: March 29, 2011
Main content:
- Requirements for practicing auditing.
- The responsibilities of the auditing firm.
- Independent audit report.
Decree 05/2019/ND-CP
Date of issue: January 22, 2019
Main content:
- Regulations regarding the organization of internal audit.
- This applies to all mandatory groups.
- Internal auditor standards.
Circular 08/2021/TT-BTC
Date of issue: January 25, 2021
Main content:
- Guidelines for internal audit standards.
- Risk assessment process.
- Audit planning methodology.
If a company already has an internal audit system, does it still need an independent audit?
This is a question we get a lot from business owners. The short answer is: Yes, and they support each other.
Why can't it be replaced?
No matter how good internal auditors are, they are still insiders. Their objectivity can be affected by pressure from superiors or the company culture. Independent auditors, with their external position, provide a level of fairness that no internal employee can replace.
Furthermore, internal audit reports are internal documents and have no legal validity when dealing with banks or tax authorities. In contrast, independent audit reports are the common language required by partners and regulatory bodies.
Supportive relationship
Internal and independent audits form a robust defense system:
- Internal auditing helps clean up the system before independent auditing arrives: When internal auditing has done a good job, independent auditing will work faster, reduce errors, and thus reduce audit fees.
- Independent audits help internal audits uncover hidden aspects: The findings of independent audits often provide excellent insights for internal audits to adjust their audit programs in subsequent years.
At MAN – Master Accountant Network, we often advise our clients to consider internal auditing as a preparatory step and independent auditing as a verification step. The seamless coordination between the two will help businesses achieve stable growth.
Case Study: Lessons from a Lack of Control
To clarify further, let's look at the case of company X, a medium-sized trading company in Ho Chi Minh City.
Situation
Company X has rapidly growing revenue but declining profits. The management doesn't understand why. They only hire an independent auditor annually to submit reports to the tax authorities. Independent auditors usually issue unqualified opinions because the basic figures match the documentation. However, leaks still occur.
How to handle it
Upon joining MAN, we conducted a thorough internal audit. The results showed that:
- The warehousing process has loopholes that allow for small but continuous losses of goods.
- The company's administrative expense system was inflated due to poorly controlled entertainment expense invoices.
Lessons learned
Independent auditors did their job correctly by verifying the financial statements (since these figures were balanced by valid invoices). However, they were not obligated to delve into warehouse operations or detailed expenditure controls. That's where internal auditing came in. After re-establishing internal control procedures, company X reduced its operating costs by 151 TP3T in just one year.
Common risks associated with a lack of coordination.
Without either of these two elements, or if they are not coordinated effectively, businesses will face the following risks:
- Tax risks: Without internal audits, businesses are prone to errors in invoices and supporting documents. When tax authorities conduct an inspection, the fines and back taxes can be substantial.
- Fraud risk: Employees or managers could exploit loopholes if internal control systems are weak.
- Reputation risk: A financial report lacking transparency or receiving an independent audit opinion will immediately reduce the company's value.
Experts at MAN – Master Accountant Network always emphasize that prevention is better than cure. The cost of maintaining internal audits is far lower than the damage caused by fraud or tax penalties.
Expert perspective on tax risk management
In reality, in Vietnam, there is a significant overlap between business administration and tax administration. Many businesses mistakenly believe that auditing is solely for the benefit of the tax authorities. This is only partially true.
Independent audits provide assurance to tax authorities regarding integrity. However, the true security of a business comes from controlling risks right from the daily accounting stage, through internal auditing.
We, the team of experts at MAN with 30 years of experience, have found that the most successful businesses are those that know how to leverage the results of independent audits to adjust their internal audit policies. This is a continuous improvement cycle that every business owner needs to master.
Conclude
Independent auditing and internal auditing, despite their differing purposes and methods, perfectly complement each other in protecting and increasing the value of a business. One ensures market confidence, the other ensures internal health. A smart manager will not choose one over the other, but will combine them into a robust risk management system.
At MAN – Master Accountant Network, with over 30 years of experience in auditing, accounting, and tax consulting, we understand that every business has unique needs. We are proud to be a partner with thousands of businesses in establishing sustainable internal control systems and optimizing tax costs in Vietnam. If your business is looking for a comprehensive solution to address financial risks, don't hesitate to contact the expert team at MAN. We are committed to providing practical solutions that help businesses confidently grow on a solid foundation.
Service contact information at MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant Network, CPA Vietnam with over 30 years of experience in accounting, auditing, taxation, and corporate financial consulting.
MAN – Master Accountant Network is committed to providing transparent, up-to-date professional information in accordance with current legal regulations and adhering to professional standards in the fields of accounting, auditing, and taxation.
Frequently Asked Questions about Independent Auditing and Internal Auditing
Is internal auditing mandatory?
According to the 2015 Accounting Law, internal auditing is mandatory for entities such as state-owned enterprises, listed companies, and financial institutions. For other private businesses, it is a governance option but is strongly encouraged to protect assets.
Can I hire an independent auditing firm to conduct an internal audit?
This could be called outsourced internal audit services. Many businesses choose this approach to ensure professionalism and save on personnel costs instead of building a complex internal audit department.
How can I tell if my internal control system is weak?
If a business frequently experiences unexplained asset losses, consistently receives delayed financial reports, or has an overly cumbersome/loose expense approval process, these are clear signs.
When is it necessary to change the independent auditing firm?
The decision to change auditors should not be based on whether audit fees are cheap or expensive, but rather on the quality of their advice and their understanding of the company's industry. However, audit rotation is also a good way to ensure objectivity.
Do internal auditors have the authority to discipline employees?
No. Internal auditors do not have the authority to manage or penalize. They have the authority to make recommendations. The authority to impose penalties rests with the Board of Directors. Internal auditors only provide information for the Board of Directors to make decisions.